Introduction
When the new regulatory frameworks for Interest Rate Risk in the Banking Book ("IRRBB") came into force, stricter requirements were placed on credit institutions' interest rate risk models. NFC was engaged to assist a Swedish niche bank in updating its existing models for both Economic Value of Equity ("EVE") and Net Interest Income ("NII") to ensure full regulatory compliance and reliability of the calculations.
In conjunction with the implementation of the new requirements, the bank had a stated ambition to streamline its processes by reducing manual intervention in calculation and reporting. Consequently, NFC was commissioned to develop, implement, and document the updated models all the way through to deployment.
Background
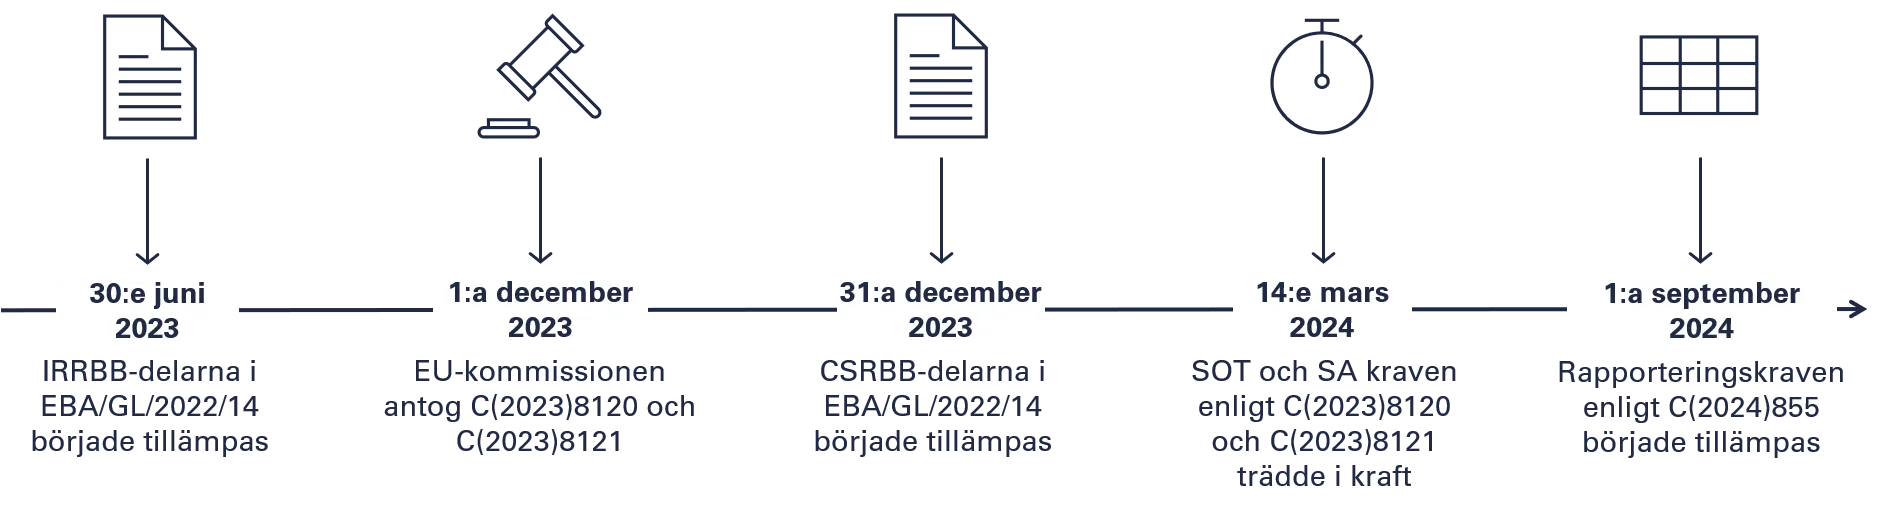
The revision of CRD IV in 2019 resulted in a revised mandate for the European Banking Authority (EBA) regarding IRRBB. Consequently, the EBA published an updated IRRBB regulatory package, including associated guidelines and technical standards, which were to be phased in during 2023 and 2024. The new standards meant that The Supervisory Outlier Test (SOT) was expanded to also encompass NII, and that new standardised methodologies and reporting templates were introduced.
For the bank, the regulatory frameworks brought increased modelling requirements and a greater need for model documentation. The regulatory updates increased both the scope and complexity of the bank’s IRRBB operations, while there was also uncertainty regarding which parts of the package were applicable given the bank’s size, business activities, and risk profile. This created a need for new calculation methodologies, expanded data collection, and more comprehensive reporting, placing higher demands on the bank’s models, systems, and governance frameworks.
Execution
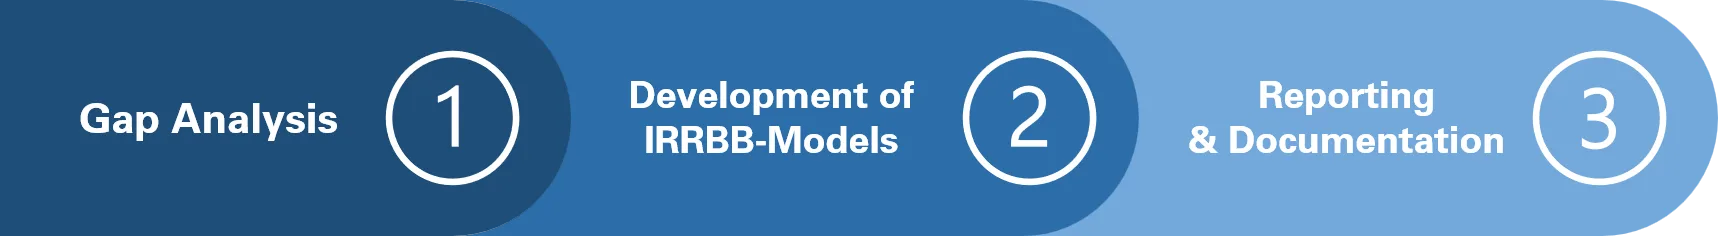
In light of these new requirements, NFC was engaged to develop the bank’s IRRBB framework. Initially, NFC mapped the bank’s existing models and processes and conducted a gap analysis, identifying areas that required adaptation to comply with the new regulatory requirements. Based on the gap analysis, recommendations were put forward regarding which components of the existing models could be retained and which deficiencies needed to be addressed.
Based on the gap analysis, NFC developed new IRRBB calculation models encompassing both EVE and NII. In consultation with the bank, the standardised methodology for IRRBB was implemented. The models were developed in Excel with automated functionality built in VBA to automatically populate the EBA reporting templates, thereby streamlining the reporting process. In parallel, the bank's IRRBB framework was adapted, and model documentation was prepared to ensure traceability and reproducibility.
Outcome
The outcome of NFC's work provided the bank with an accurate and efficient model for calculating EVE and NII, aligned with the new regulatory frameworks. The accompanying model documentation enhances transparency and traceability within the model framework, facilitating future audits and ongoing development. The automated and streamlined process for IRRBB calculation and the population of the EBA reporting templates saves time during reporting and reduces the risk of manual error, freeing up resources for analysis.
By tailoring the model to the bank’s needs, applying the standardised methodology, and calculating the SOT, full regulatory compliance and robust risk management were ensured. This also mitigated the risk of supervisory sanctions from the Swedish Financial Supervisory Authority (Finansinspektionen), thereby strengthening the bank’s regulatory standing.
The new EVE model, which NFC assisted the bank in implementing, was adapted to exclude commercial margins in accordance with the bank’s internal risk management. As a result, the SOT outcome has become lower and more representative. This change enhances the model’s risk sensitivity and increases transparency in the bank’s IRRBB reporting.
The project demonstrates how NFC combines expertise in IRRBB, process automation, and regulatory interpretation to deliver efficient solutions that meet all regulatory requirements. Is this relevant to your organisation? Read more about our risk modelling and model validation services or contact us directly to find out more!